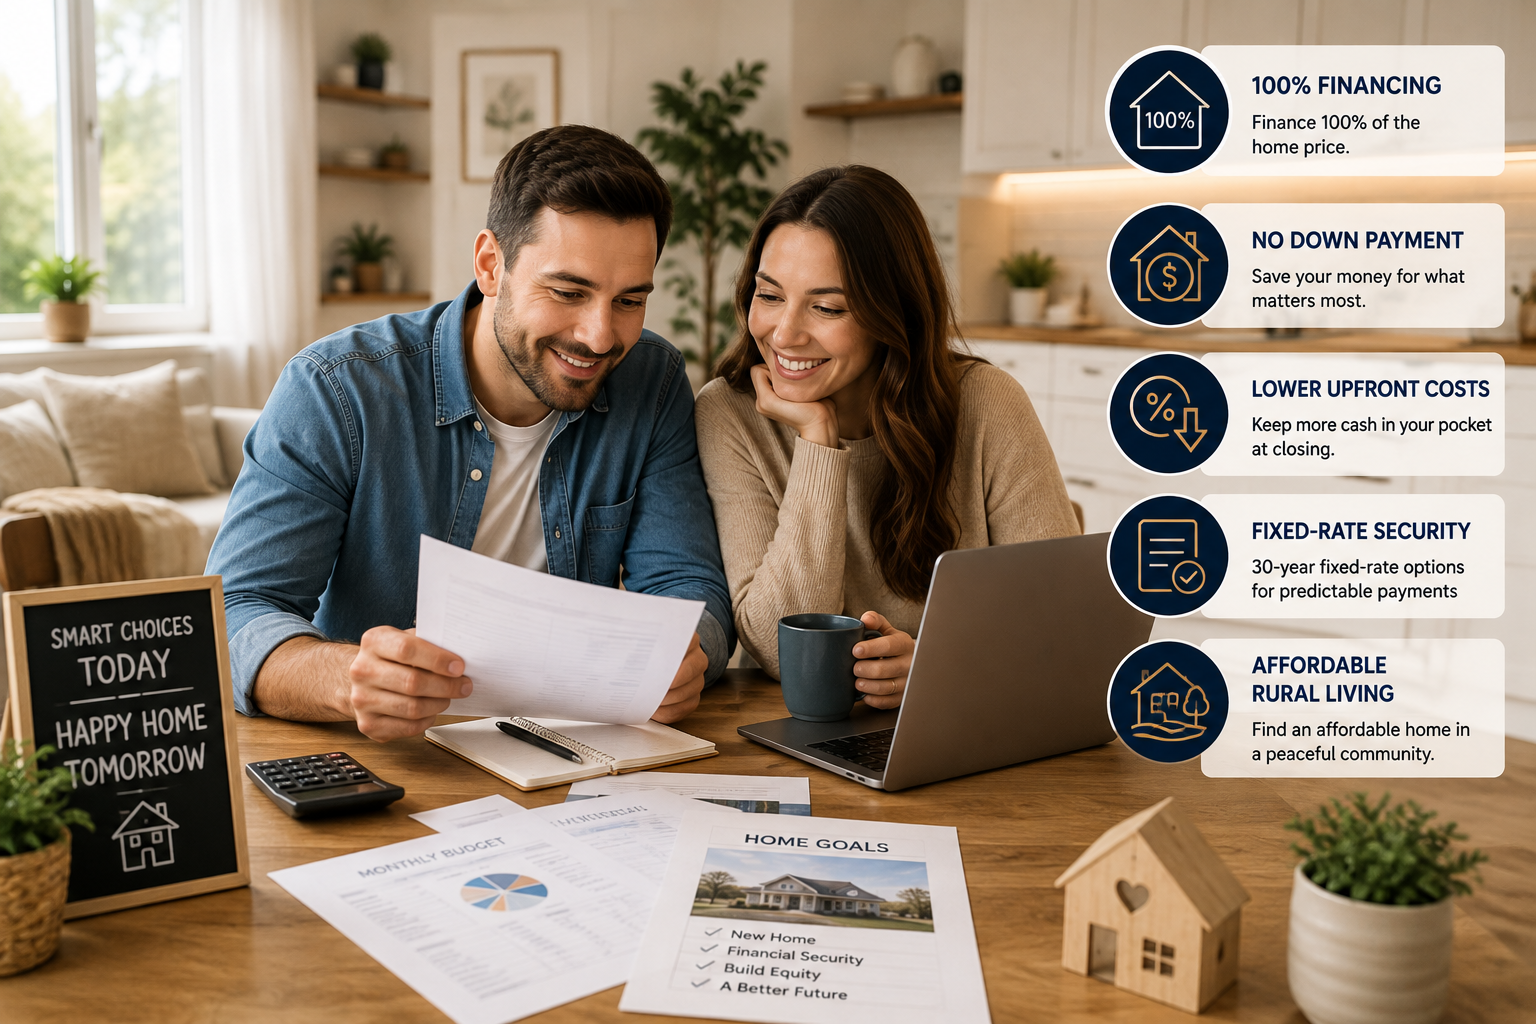
Make homeownership more accessible with a USDA Loan designed for qualified buyers purchasing a home in an eligible rural or suburban area. With 100% financing options and competitive 30-year fixed-rate financing, a USDA Loan can help eligible buyers purchase a home without a traditional down payment.
A USDA Loan is a government-backed mortgage program designed to help eligible low- and moderate-income households purchase a safe, affordable primary residence in an eligible rural area.
Through the USDA Single Family Housing Guaranteed Loan Program, qualified borrowers may be able to purchase or build a home with 100% financing, subject to USDA and lender requirements.
Eligible properties can include new or existing homes, certain condos, PUDs, modular homes, and manufactured homes that meet program guidelines.
Qualified borrowers may be able to finance 100% of the purchase price, reducing the need for a traditional down payment.
No traditional down payment required for eligible borrowers. Preserve savings for closing costs, moving expenses, and more.
The USDA program offers 30-year fixed-rate financing with predictable principal and interest payments.
USDA itself does not establish a minimum credit score; lenders may apply their own standards.
Many smaller communities and suburban areas may qualify. Check the address to verify eligibility.
A USDA Loan can help qualified first-time buyers purchase a home without saving for a traditional down payment.
If you're considering a home outside a major metropolitan area, check whether the property falls within an eligible USDA area.
Preserve more of your savings by taking advantage of available 100% financing when you qualify.
Purchase a suitable primary residence in an eligible community while keeping upfront costs manageable.
USDA financing has specific income, property, occupancy, and underwriting requirements. Our team helps you understand those requirements before you move forward.
We'll help evaluate your situation, verify eligibility, compare available financing options, and guide you from pre-approval through closing.
We'll review your income, credit profile, household information, and homeownership goals.
We'll determine whether the property is located in a USDA-eligible area and meets requirements.
Once your profile is reviewed, we'll help determine your purchasing power and options.
Complete underwriting, appraisal, and final documentation before closing on your new home.
You may not need a large down payment to buy a home. If your income and property meet USDA requirements, a USDA Loan could provide an affordable path toward homeownership.
Get USDA Pre-Approved Today